Insurance guide
Replacement Cost vs. Market Value
Why a home's insurance limit is based on rebuilding cost rather than its sale price.
Educational examples updated . This update does not represent a new staff or legal review.
What to compare in your policy
Use a property-specific rebuilding estimate. Then examine extended replacement cost, code-upgrade coverage, and how the policy settles a partial or total loss.
These are educational benchmarks, not a recommendation for every applicant.Market value reflects what a buyer may pay for the home and land. Replacement cost estimates what it may cost to rebuild the insured structure with comparable materials and labor after a covered total loss.
Land value, neighborhood demand, demolition, debris removal, building-code requirements, labor, and material costs can cause the two figures to differ substantially. A higher purchase price does not always require the same amount of dwelling coverage, and a lower purchase price does not mean reconstruction will be inexpensive.
Review the replacement-cost estimate for the home's square footage, construction features, finishes, attached structures, and improvements. Update the estimate after major renovations or additions.
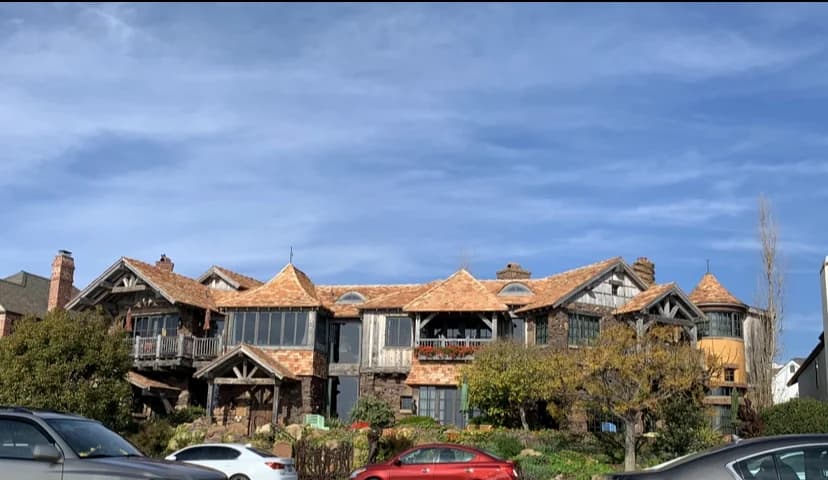
A sale price and a rebuilding estimate answer different questions
Hypothetical example: a Yorba Linda home sells for $1.1 million, but a detailed estimate puts reconstruction at $650,000. The difference does not automatically mean the insurance is too low: the sale includes land and location. Conversely, an inexpensive property can be costly to rebuild. Neither number should be copied into the policy without checking the structure's details.
Replacement cost means the cost to repair or replace with comparable new materials, subject to the contract. Actual cash value reflects depreciation for age and condition. A replacement-cost policy can initially pay a depreciated amount and release additional eligible funds after repairs; ask about the proof and deadlines.
Look beyond the main dwelling limit
Extended replacement cost is an endorsement—an amendment to the policy—that adds a specified cushion above the dwelling limit when its conditions are met. It is not an unlimited promise. Ordinance or law coverage addresses eligible extra costs of complying with current building codes after a covered loss. Ask us to review those provisions alongside demolition, debris removal, and your updated kitchen, roof, or addition.